Justin discusses why hedge funds should be part of your investment portfolio using the example of Naspers to demonstrate how we are able to extract value from an opportunity without having to take a directional view on the underlying company.
- article
- 31 January 2023
We often talk about how hedge funds have more investment ‘tools’ than more traditional long-only funds do. Using the example of Naspers, I’d like to demonstrate how we are able to extract value from an opportunity without having to take a directional view on the underlying company. Short selling is typically associated with ‘betting against a company’ or ‘exposing fraud’. While these are certainly strong motivations to engage in short selling, there are a host of other reasons why a hedge fund manager might use this tool to generate returns. One of the most common motivations for engaging in short selling is arbitrage trades that attempt to take advantage of holding company discounts.
Naspers and Prosus serve as the perfect example to demonstrate how we engage in such trades to generate returns for our investors. The value of this tool is that it allows us to generate returns for our funds that have no reliance on the market (or even the underlying share price) going up. For this discussion, we will refer to both Naspers and Prosus as “Naspers”, as these entities reference the same underlying assets. Naspers is an investment holding company that owns a significant interest in Tencent, the gaming and social networking giant in China. Tencent has been the jewel in the Naspers crown for many years, propelling Naspers to the top of the list of the most valuable companies on the JSE. Unfortunately, Tencent’s success eventually became a burden for Naspers, as it grew so large that it accounted for 25% of the JSE’s total market capitalisation. The better Tencent did, and the larger Naspers grew, the wider the discount to the underlying assets became.
When we undertook our due diligence on the company for the first time, the discount to the underlying assets was approximately 20%. As the years passed, the discount got ever wider, eventually reaching a peak of 71% at Naspers. At that time, there was approximately $100bn worth of trapped value between Naspers and Prosus and investors had just about given up hope. The Naspers management team has been aware of this significant problem for the better part of the past six years given the persistent pressure from shareholders to find a solution for the discount.
They engaged in several transactions that were aimed at structurally solving the discount, but their actions made the situation progressively worse, resulting in an ever-wider discount. Matters went from bad to worse earlier this year when Russia invaded Ukraine. In addition to being forced to write off or sell their interests in Russian assets VK and Avito, shareholders concluded that Naspers exposure to China and Russia presented unacceptably high risks and proceeded to sell Naspers shares indiscriminately. It was at this point that the discount to the underlying assets at Naspers reached its peak level of 71% in May 2022.
Back in 2018, Peregrine Capital wrote to the board of directors of Naspers, advocating for a series of transactions whereby Naspers would sell Tencent shares and repurchase Naspers shares. This transaction was effectively a risk-free way to continuously sell Tencent at its market price and immediately repurchase those same Tencent shares (via Naspers) at a 40% discount to the underlying asset value at that time.
By selling an asset for 100% of its value and immediately repurchasing that same asset for 60% of its value, Naspers had an incredible risk-free opportunity to accelerate per share value growth for Naspers shareholders by exploiting the wide discount. It is our firm belief that the discount is out of management’s control but presents an incredible opportunity to accelerate per share value growth in the manner described. While our letter was disregarded in 2018, the Naspers management team, to their credit, dusted off this solution and announced an open-ended share repurchase programme of Naspers and Prosus shares, funded by the disposal of Tencent shares on the 27th of June 2022. The result of this announcement was the immediate narrowing of the holding company discount. While the announcement was positively received by the market, the discount persisted at very high levels for two days following the announcement of the transaction.
While we missed the first move upwards, our team was convinced that there was further narrowing of the discount to come, especially if management used their self-proclaimed “bazooka” in the weeks following the announcement. Rather than simply buying Naspers shares, we used our ability to short sell to construct a trade that gave us exposure to all Naspers assets, other than Tencent. Mechanically, we purchased Naspers shares and short sold the Tencent shares against the Naspers shares we owned. This trade gave us direct exposure to the highly undervalued ‘Naspers rump assets’, allowing us to benefit from a narrowing of the discount when it was at approximately 55%. We were not forced to take a company specific view on Tencent, which has been navigating choppy regulatory waters in China. We knew that the wider the discounts became, the more shares Naspers could repurchase with their Tencent sales proceeds.
We also knew that Naspers would be buying our long positions and selling our short position, so the technical supply/demand dynamics were in our favour. Our funds were able to generate low risk returns of approximately 20% on this trade as the Naspers discount narrowed to 40% over the coming months. The Naspers example demonstrates very clearly how short selling can be used to neutralise exposure to a component of a company you don’t like. Instead of adding more market risk by buying Tencent within Naspers, we were able to neutralise the Tencent exposure by short selling the Tencent exposure within Naspers. It is important to emphasise that this sort of opportunity is not generally available to managers of long-only funds.
For the average long-only fund, benefitting from the Naspers discount reduction requires that you own Naspers, forcing you to take a specific view on Tencent. Hedge funds have the flexibility to simply not have a view, which is an incredibly valuable tool to have at one’s disposal in this type of market environment. Arbitrage trades aimed at taking advantage of holding company discounts have proved to be a highly effective and differentiated means of generating returns for our investors as a hedge fund manager.
In the News
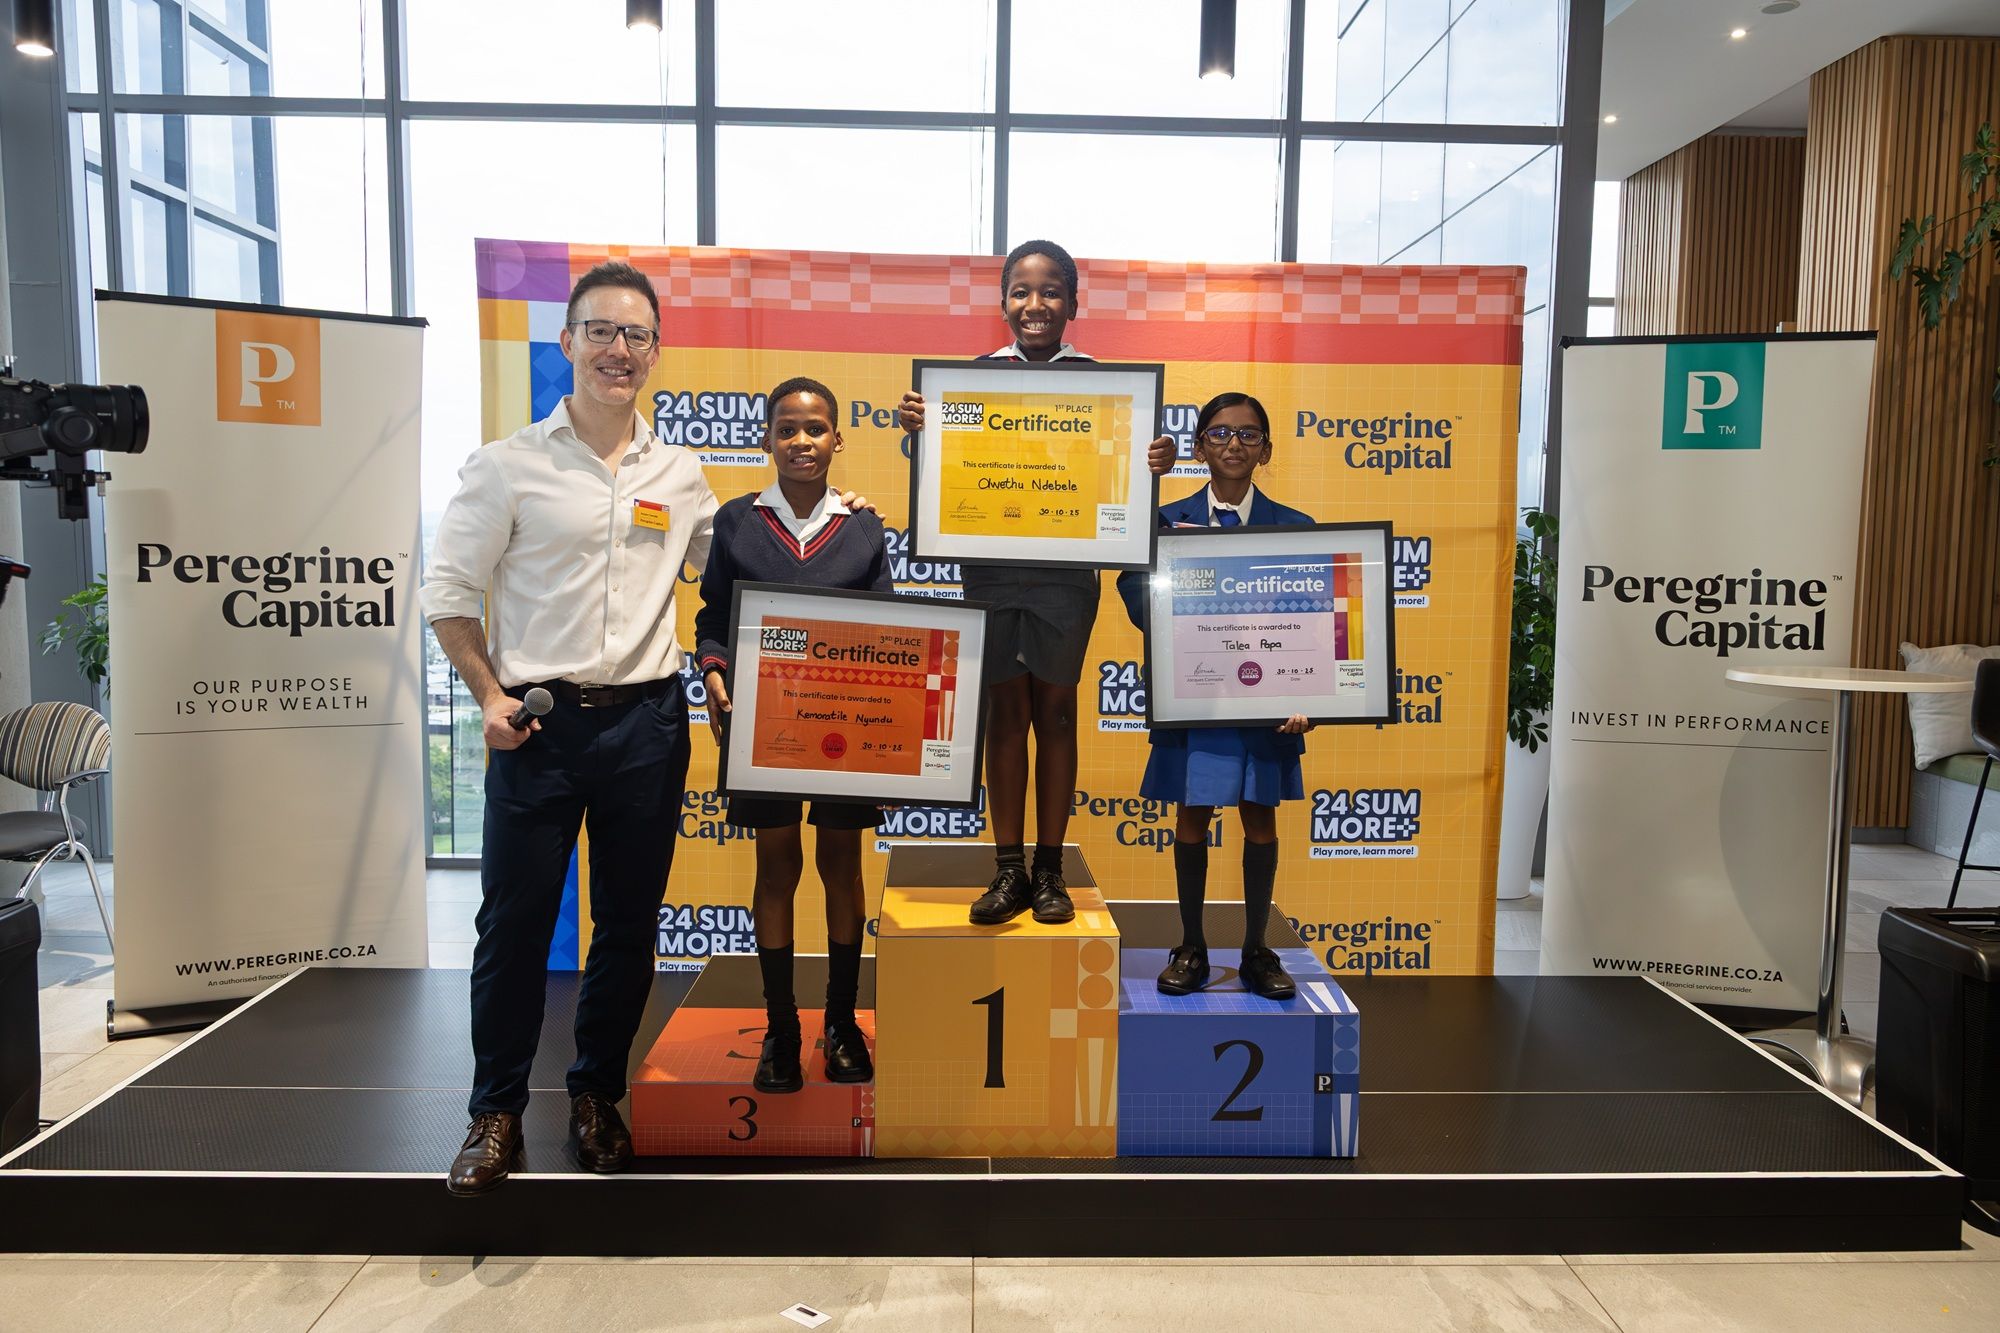
South Africa’s Young Maths Champions Prepare to Make 24 as Peregrine Capital 24SumMore National Final Looms
Can you make 24? Grade 4 – 6 maths champions from 300+ schools compete in the Peregrine Capital 24SumMore national final in Johannesburg on 29 October 2026.
- article
- 3 min read
- 29 September 2026
In the News
The Many Hats a Financial Advisor Wears
Ask most people what a financial advisor does and you get some version of the same answer: they pick investments. That is the visible part of the job, in the way that a prescription is the visible part of what a doctor does. The value sits in everything that happens before it. Writing for Moneyweb, Anne Holding, an investment specialist at Peregrine Capital, sets out the roles a good advisor takes on across an investor's life. Specialist, demystifier, coach, therapist, architect. She also explains why much of that work leaves nothing to point to, because its purpose was prevention.
- article
- 3 min read
- 15 September 2026
In the News
Leading Beyond the Numbers
"Technical competence is the entry ticket, not the differentiator." That line, from Tania Formilan, CFO and COO at Peregrine Capital, is a fair test for anyone building a career in this industry. At a senior level, everyone can do the numbers. What separates people is lateral thinking, judgement, integrity, and the ability to build genuine trust with clients and colleagues. Tania qualified as a CA(SA) in 2000 and joined Peregrine more than 25 years ago, moving from a finance role into operational leadership as the business grew. In that time she has watched South African hedge funds shift from a largely unregulated corner of the market, viewed with scepticism by the broader investment community, to a regulated part of the collective investment landscape, held to the same standards of governance, transparency and risk management as any other asset manager. On what matters most: never lose sight of the fact that people, not processes, get things done. Companies succeed when their people do. Her full interview appears in the Women in Hedge Funds II special report, published by HedgeNews Africa. Our thanks to HedgeNews Africa and Tania Formilan.
- article
- 3 min read
- 26 August 2026
Stay connected
Subscribe to Peregrine Capital's regular communications. Gain access to up-to-date news and insights from our world of Hedge Funds, delivered straight to your inbox.
Stay informed. Stay Educated.